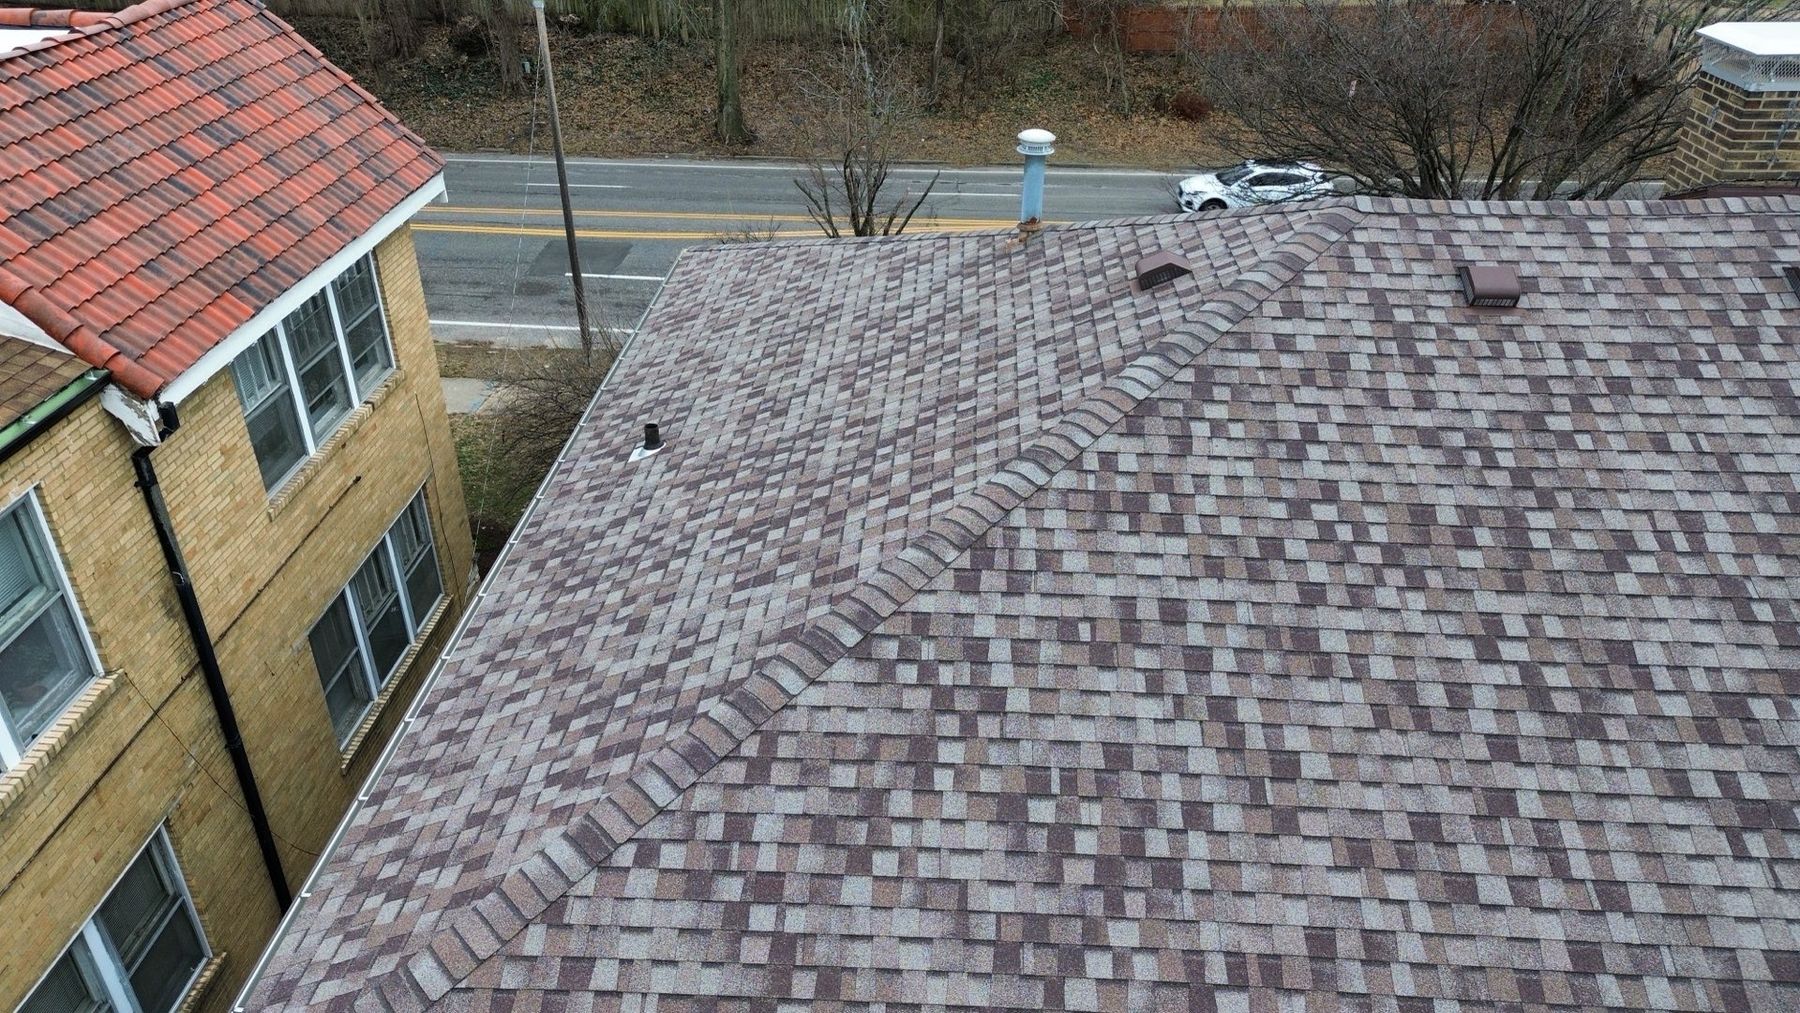
What We Handle on Your Claim, and What Stays Yours
Missouri law does not permit a roofing contractor to negotiate your insurance claim, and we will not pretend otherwise. The claim stays yours. We are roofers, not insurance agents, adjusters or attorneys, nothing on this page is coverage or legal advice, and your policy is the final word.
What Keys Roofing handles is the documentation and the coordination:
- A free roof inspection, photographed section by section, before you file.
- Meeting your adjuster at the property as the contractor.
- Reading the carrier's scope of loss with you line by line.
- Supplements built on photos and documentation when the scope comes up short.
- The insurance paperwork and carrier coordination, including the completion paperwork that releases held-back depreciation.
What we will not do: promise an approval, a dollar amount or a timeline, tell you a roof has hail damage when it does not, inflate a scope, or play games with your deductible.
Before You File: An Honest Inspection
Do not file a claim on a guess. A claim that gets denied does you no good, so the first move is getting the roof inspected and photographed by someone who knows what hail damage actually looks like. Keys Roofing inspections are free. We photograph the roof section by section, ridge down to the gutter line, and after a storm we photograph the collateral damage around the house too: AC condenser fins, fences, decks, window screens and siding. See how we inspect a roof and our free roof inspection page.
Then we go through the photos with you and tell you straight whether what we found is worth a claim. Sometimes it is not, and we say so. If the marks on your roof are blisters rather than hail bruises, you hear that from us before you ever file. Those photos also establish what the roof looked like close to the storm date, which matters once the claim is open. For what hail and wind damage looks like, see hail and storm damage roof repair.
Filing the Claim and Getting Ready for the Adjuster
If the damage is real, you open the claim with your carrier, by phone or online. You will get a claim number and, eventually, an adjuster assignment. Keep every document and write down every date. Before the adjuster comes out, have these ready:
- The basics, written down. Your claim number, the date you filed, and the date of the storm you are claiming for, so there is no confusion about which event is being assessed.
- Your inspection documentation. Photos, dates and a written summary of what was found, so you are not relying on memory.
- Your declarations page. Find your wind and hail deductible and whether it is a flat amount or a percentage of your home's insured value. More in roof deductibles, straight talk.
- Your own notes. Spots with recurring water intrusion, changes you have noticed since the storm, and areas that are hard to see from the ground. You know your house better than anyone walking it for the first time.
The full list is in the insurance adjuster meeting: how to be ready.
The Adjuster Meeting: What Gets Checked
The adjuster meeting is a documentation and assessment visit. The adjuster inspects the property, notes visible damage and records findings that go back to your carrier. It is not a negotiation in the moment, and it is not the final word on your claim. We think a homeowner should never do this meeting alone, so we attend as the contractor, walk the roof with the adjuster, and make sure everything we documented gets looked at rather than glossed over. Kaleb, who owns Keys Roofing, personally walks storm-damaged roofs and adjuster meetings with his crew.
The adjuster is not your enemy. Missed evidence, not bad faith, is what shortchanges most claims. Here is what the adjuster is typically evaluating, covered in full in what the insurance adjuster is actually looking for:
- Test squares. A marked-off section on each slope, typically ten feet by ten feet, where qualifying hail impacts get counted. Carriers apply different thresholds, so we will not quote you a magic number. Because our inspection comes first, we already know which slopes carry the evidence.
- Soft metals and collateral. Dents in vents, gutters and AC fins help show that meaningful hail hit your address specifically, not just your zip code.
- Hail versus wind versus age. The adjuster separates real hail bruises from blistering and normal wear, and sorts out which damage came from wind, because it affects how the scope gets written.
Ask the adjuster what they observed, and save the coverage questions for your carrier. Those answers come through the formal claims process, not verbally on the roof.
The Scope of Loss and Your First Check
If the claim is approved, the carrier issues a scope of loss: a line-item list of what they agree to pay for. On most replacement-cost policies, the money comes in pieces:
- The first check is the actual cash value: the replacement cost minus depreciation for the roof's age, and minus your deductible.
- Your deductible is your share of the loss, set by your policy and paid by you. Missouri law prohibits contractors from paying, waiving or rebating it, and Keys Roofing will not offer to.
- Recoverable depreciation is held back by the carrier and released after the work is completed and invoiced.
Exact amounts depend entirely on your policy. We go through the scope with you line by line before the build starts, because missed items are common. If you already have a scope in hand and something about it looks light, bring it to us.
Supplements: When the First Number Is Not Final
The scope is a first draft. The adjuster had limited time on the roof and priced the job from standardized software, so line items get missed, out of volume, not malice. A supplement is the formal request, with documentation attached, to add or correct line items so the scope matches the actual job. The common, legitimate reasons:
- Damage that only shows at tear-off. Nobody can see the decking until the shingles come off. If we find rotted or broken deck boards, we photograph them where they lie and submit exactly what we found.
- Code and manufacturer requirements. Underlayment, ice and water protection where required, drip edge, ventilation components, starter course and the flashing details the installation spec calls for.
- Access and complexity. Steep pitches, high or difficult access, or a two-layer tear-off scoped as one layer. That is not a negotiation, it is a correction.
Every supplement we file is built on photos of the actual condition and the measurement or spec behind each line item, never padding. Whether it is approved, and for how much, is the carrier's call, and we will not promise either. More in what a supplement is and when the adjuster's first number is not final.
The Build and the Last Check
Nothing about the insurance process changes how we build. Once the scope is settled, we handle the scheduling, permits and inspections, order the materials and replace the roof to manufacturer spec: tear-off, deck check, underlayment, flashing, shingles, cleanup, and a final photo record of the completed work. Keys Roofing installs Atlas and Malarkey shingles, and our roof replacement page covers the build in detail.
Then comes the step homeowners forget. After the work is complete, the completion paperwork goes to the carrier, and they release the recoverable depreciation they held back. If that final invoice never gets sent, that money never shows up. Our office handles this filing as part of the job, because leaving the last check uncollected is one of the most common ways homeowners lose money on a claim they already won. The whole sequence is in a hail claim from start to finish.
Where We Help With Roof Claims
Keys Roofing helps homeowners with roof insurance claims throughout St. Louis County, including Chesterfield, Ladue, Frontenac, Town and Country, Clayton, Kirkwood, Webster Groves, Creve Coeur, Wildwood, Ballwin, Olivette, Brentwood, Richmond Heights and University City. We also cover Sunset Hills, Crestwood, Maryland Heights, Valley Park, Eureka, Fenton, Oakville, Sappington, Affton and Overland, and beyond the county line in St. Charles, O'Fallon, Wentzville and Arnold, all within a 50-mile service radius. We respond to every inquiry within 24 hours: call (314) 220-2333, Monday through Saturday, 7am to 7pm.